If you own a home in New Jersey with an FHA or VA loan and you are carrying credit card balances at 22% to 27%, your home equity may be a cheaper way to pay that debt. Even if your current mortgage rate is 5% and today's rate is about 7%, the interest you stop paying on the high-rate debt can outweigh the higher mortgage payment. Here is a worked example that includes FHA mortgage insurance.
The example borrower (hypothetical, not a quote)
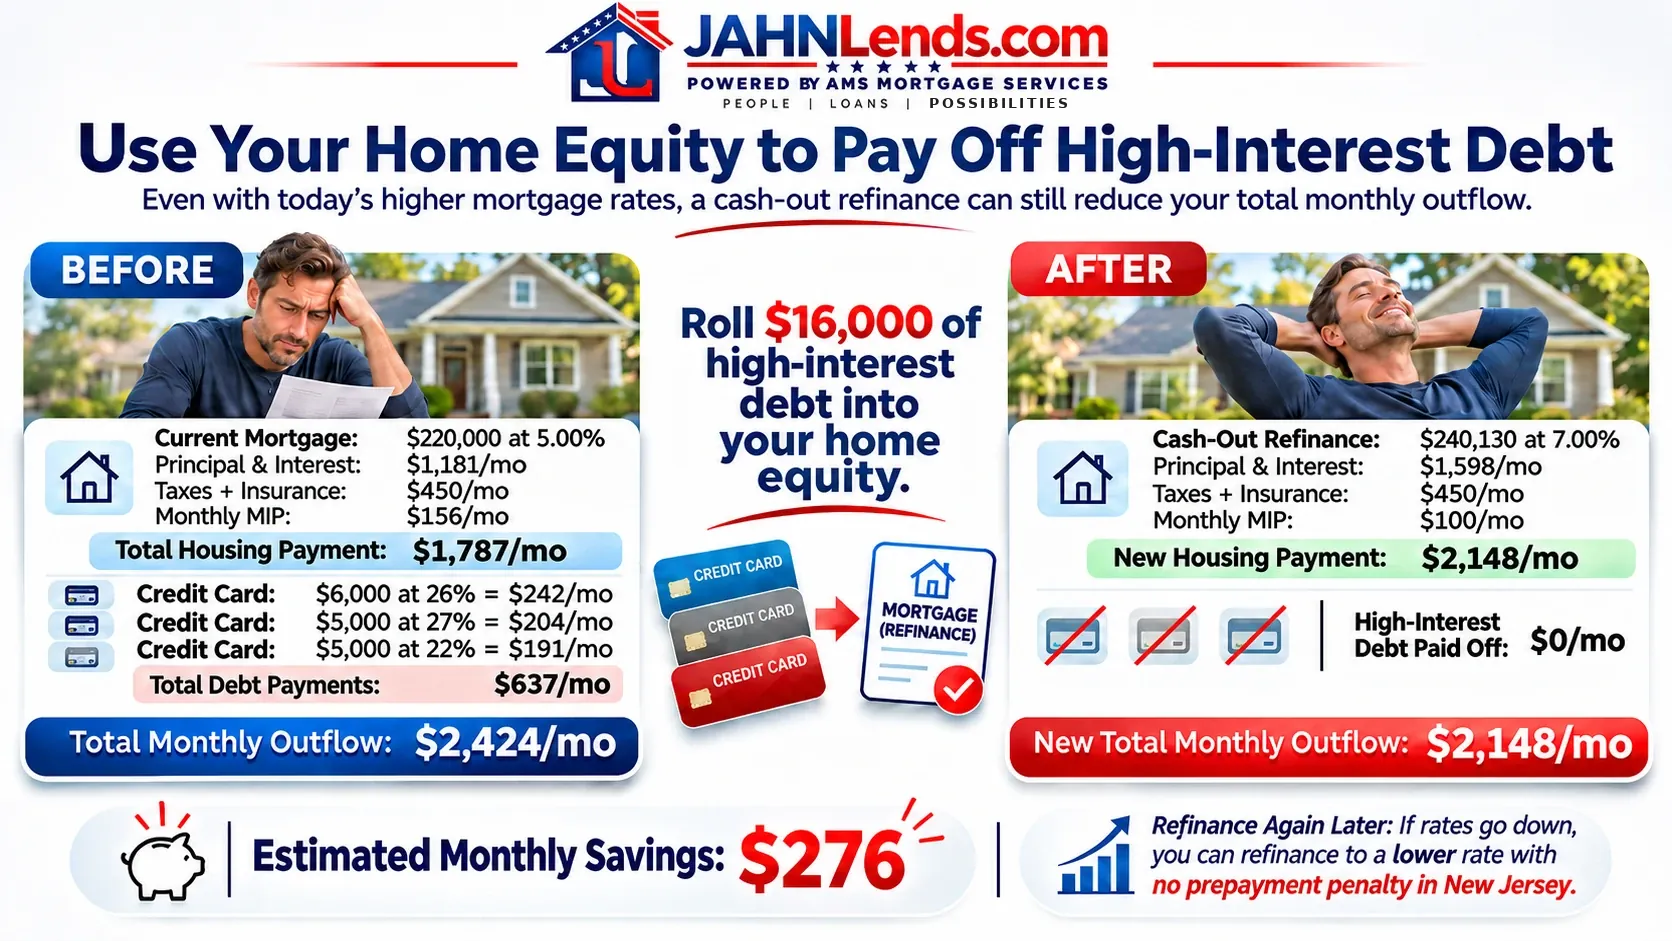
- Current mortgage: $220,000 FHA loan at 5%, 30-year fixed. Principal and interest: $1,181 per month. Taxes and homeowners insurance: $450 per month. Annual mortgage insurance premium (MIP) at 0.85%: $156 per month. Current payment with MIP: $1,787.
- High-interest debt: $16,000 total, made up of a $6,000 card at 26%, a $5,000 card at 27% and a $5,000 card at 22%.
- Equity: a typical New Jersey home is worth about $400,000. The new loan of about $240,000 is roughly 60% of that value, well inside the commonly used 80% limit for an FHA cash-out refinance.
What the debt costs each month today
| Debt | Balance | Rate | Monthly payment |
|---|---|---|---|
| Credit card | $6,000 | 26% | $242 |
| Credit card | $5,000 | 27% | $204 |
| Credit card | $5,000 | 22% | $191 |
| Total | $16,000 | $637 |
Card payments assume each balance is paid off over 3 years.
After an FHA cash-out refinance at 7%
The new loan is $236,000 (the $220,000 payoff plus the $16,000 of card debt) plus the 1.75% upfront mortgage insurance premium of $4,130, which is rolled into the loan. That makes the new loan amount $240,130.
| Before | After | |
|---|---|---|
| Mortgage balance | $220,000 at 5% | $240,130 at 7% |
| Principal and interest | $1,181 | $1,598 |
| Taxes and insurance | $450 | $450 |
| Monthly mortgage insurance (MIP) | $156 (0.85%) | $100 (0.50%) |
| PITI + MI | $1,787 | $2,148 |
| Credit card payments | $637 | $0 |
| Total monthly outflow | $2,424 | $2,148 |
In this example the total drops by an estimated $276 per month, even though the mortgage rate went up two points. Part of the reason is mortgage insurance. Older FHA loans often carry a 0.85% annual premium. A cash-out refinance at 80% loan-to-value or lower qualifies for the lower 0.50% rate, which trims the monthly insurance cost.
What is not included
- Closing costs. They are typically a few percent of the loan. If rolled into the loan, they raise the new payment.
- VA loans. There is no monthly mortgage insurance on a VA loan, but there is a funding fee on a cash-out refinance (2.15% to 3.3% depending on use) unless you are exempt. It is usually rolled into the loan and raises the payment.
- Your actual MIP rate. It depends on when your current loan was originated, its loan-to-value and its term. We confirm it on your real loan.
- A longer payoff. You are moving debt that would be paid off in about 3 years into a 30-year loan. You pay it down more slowly unless you add extra principal.
- Equity limits. FHA cash-out is commonly limited to about 80% of the home's value. VA cash-out can go higher with some lenders.
When this works and when it does not
The size of the debt compared with your mortgage matters. On a $220,000 balance, moving the whole loan from 5% to 7% costs about $283 more per month in principal and interest before you add any debt. The debt you pay off has to be large enough to cover that. We run your real numbers before you decide, and we will tell you plainly if the refinance does not help.
You can refinance again if rates fall
Most residential mortgages in New Jersey do not carry a prepayment penalty, so you can refinance again if rates come down. We confirm this for your specific loan before you sign.
Frequently asked questions
Can I do this with an FHA loan?
Yes, an FHA cash-out refinance can be used to pay off debt, subject to equity and credit requirements. FHA mortgage insurance applies and is included in the example above.
What about a VA loan?
Eligible veterans can use a VA cash-out refinance, and some lenders allow a higher loan-to-value than FHA. There is no monthly mortgage insurance, but a funding fee applies unless you are exempt.
Will paying off cards hurt my credit?
Paying off revolving balances usually lowers your utilization, which often helps scores. Closing the accounts or opening new credit can have other effects.
How do I find out my real numbers?
Call (732) 754-7474 or start on our pre-approval page. See also our guides to cash-out refinance in NJ and cash-out refinance vs. HELOC.
See what your payment could look like →
This example is hypothetical and for illustration only. Your rates, payments, mortgage insurance, closing costs and savings will differ. Rates, terms, LTV limits and fees vary by lender and program and change without notice. A refinance replaces your existing loan, and the new loan may cost more over its life. JahnLends is the Woodbridge, NJ branch of AMS Mortgage Services, NMLS# 145742. Equal Housing Opportunity. For information purposes only. This is not a commitment to lend or extend credit. All loans are subject to credit approval. Other restrictions may apply.